
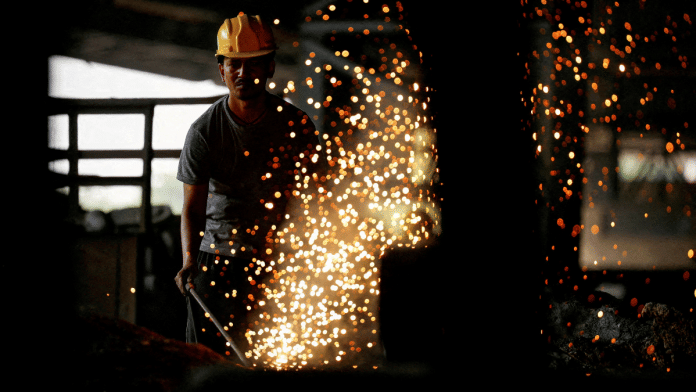
New Delhi: India’s rapid rise as the world’s second-largest steel producer has been accompanied by strong profitability, but a new working paper has questioned how much of this performance reflects genuine efficiency and how much is the result of policy protection.
The paper, ‘Competitive Steel, Competitive India’, by Shishir Gupta and Rishita Sachdeva of the Centre for Social and Economic Progress (CSEP), says India’s steel industry has benefited from a combination of cheaper domestic iron ore, import protection and restrictions on foreign competition.
India produced less than 5 percent of the world’s steel and ranked ninth globally in 2000. By 2025, it had become the second-largest producer, accounting for nearly 9 percent of global output, behind only China.
Domestic crude steel production rose from 28 million metric tonnes in FY2002 to 152 million metric tonnes in FY2025. The industry has also remained more profitable than other manufacturing sectors. Its average earnings before interest, tax, depreciation and amortisation (EBITDA) as a share of sales stood at 15 percent between 2000 and 2025, around 3-4 percentage points higher than the rest of India’s manufacturing sector.
However, the authors argue that high profitability alone does not establish that the sector is globally competitive.
“High growth and profitability can emanate either when the industry is efficient or when it is protected,” the paper says, adding that the key question is whether the industry’s performance is driven by competitive strengths or policy support.
Cheap iron ore, expensive steel
According to the paper, India’s iron ore policies have helped steelmakers access the raw material at prices significantly below international levels.
India is self-sufficient in iron ore, with around 98 percent of it used for steelmaking. Since the mid-2000s, export restrictions—including a Rs 300 per tonne duty introduced in 2007 and a 30 percent duty on high-grade ore from 2011 onwards—have sought to ensure domestic availability and contain prices.
As a result, the authors estimate that domestic iron ore prices have remained around 30-40 percent below global prices.
The paper argues that this creates an implicit transfer of value from the mining sector to steel manufacturers. “And since the bulk of iron ore is produced by the public sector, and steel is largely owned by the private sector, this transfer is from the public to the private sector,” the authors said.
At the same time, Indian steelmakers are protected from foreign competition through import tariffs and non-tariff barriers.
Steel imports face a tariff of around 7.5 percent, in addition to an 11.5 percent safeguard duty. This is against 3-4 percent tariffs in the Association of Southeast Asian Nations (ASEAN) and China.
The industry is also protected through non-tariff barriers such as Quality Control Orders (QCOs), which cover 228 steel products. However, the paper notes that as of September 2026, QCOs had been suspended for 59 products.
These restrictions allow domestic producers to charge higher prices. The paper estimates that Indian steel is around 6 percent more expensive than Japanese steel, despite India having lower production costs in several key areas.
A comparison of key costs, including wages, financing, logistics and coking coal, showed that India’s largest private steelmaker has a per-tonne production cost nearly 20-40 percent lower than Japan’s largest steel producer, said the paper.
However, these advantages do not fully translate into cheaper steel for domestic consumers.
The authors said higher steel prices negatively affect downstream industries such as construction and automobiles. Steel typically accounts for around 15 percent of the total cost of a construction project and roughly 5 percent of the raw material cost of a four-wheeler.
Suggested policy changes
The working paper recommends a calibrated 5-10-year roadmap to reduce steel tariffs and non-tariff barriers to levels comparable with ASEAN economies. Anti-dumping and countervailing duties, it says, should be used only when there is evidence of unfair trade.
The paper also recommends removing QCOs on a large number of steel products to make it easier for downstream industries, particularly smaller manufacturers and exporters, to access competitively priced inputs.
It also calls for the phased disinvestment of the government’s stake in Steel Authority of India Ltd (SAIL), while retaining a strategic minority holding. “Given the predominance of the private sector in the steel industry, there is no reason the Government of India should be actively managing a steel firm,” the authors said.
The working paper further recommends removing the 30 percent export duty on high-grade iron ore. According to the authors, allowing exports would raise the value of domestic ore, expose steelmakers to its true economic cost and encourage greater exploration.
The authors also proposed changes to the mining auction system. At present, companies that discover mineral deposits do not have the right to sell or transfer the mining rights. The paper argues that allowing explorers to monetise discoveries could revive exploration activity, which it says has “virtually stopped” in several areas.
The authors concluded that India’s steel sector must become more competitive not only by expanding production, but also by lowering costs for industries that depend on steel. “Competitive steel is a necessary condition for competitive manufacturing,” the authors said.
(Edited by Chingkheinganbi Mayengbam)
Also Read: UK nationalises British Steel, ending 6-year Chinese control. Beijing fumes