

The Narendra Modi government appears to be on a disinvestment drive. This is happening after a slow and halting implementation of its policy on the strategic sale of public-sector undertakings (PSUs) that it had announced in 2021.
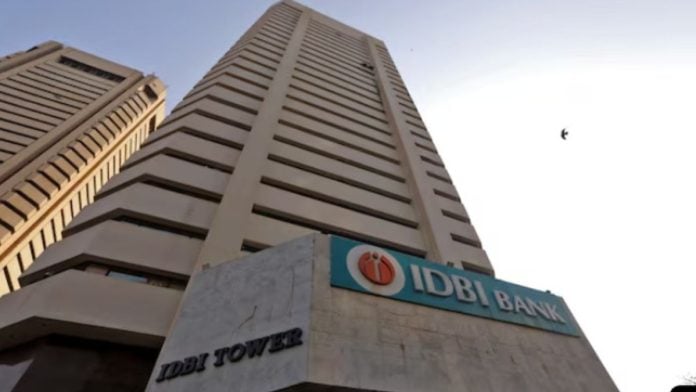
Last week, the Union Cabinet approved a proposal to sell over 30 per cent of the government’s total equity in IDBI Bank at a price that should yield the central exchequer a disinvestment receipt of over 26,500 crore in the current year.
With more than five months to go before the current year ends, the government will have collected more than its annual target of 80,000 crore from such asset sales during 2026-27. Equally important, the IDBI Bank deal means that the Modi government has now given a push to privatisation after a pause.
It is also important to note that the IDBI Bank privatisation doesn’t appear to be a flash in the pan. According to the finance ministry, the government plans to list three more PSUs on the stock exchange — India Infrastructure Finance Company Ltd (IIFCL), Mahanadi Coalfields Ltd (MCL) and South Eastern Coalfields Ltd (SECL).
Listing MCL and SECL may not result in any disinvestment receipts for the government, as they are wholly-owned subsidiaries of Coal India Ltd (CIL), which alone will benefit from such share sale proceeds. But the listing decision on IIFCL, wholly owned by the government, will mean more disinvestment receipts if it is listed before March 2027 as planned.
Indeed, preparations for an initial public offer of IIFCL shares have already begun.
Privatisation record remains unimpressive
To be sure, the government’s track record on privatisation so far has been unimpressive. After formulating a policy on strategic disinvestment in 2021, wherein the government decided to exit all PSUs barring a few strategic ones, only Air India, Ferro Scrap Nigam, Neelachal Ispat Nigam and Indian Medicines Pharmaceuticals Corporation have been privatised.
Air India was a high-profile company, but owing to its huge, accumulated debt, the net proceeds for the government from its privatisation in January 2022 were only 2,700 crore.
Not that the sale of the other three companies saw higher realisation. The privatisation of Ferro Scrap and Neelachal Ispat yielded zero receipts. The sale proceeds from Indian Medicines Pharmaceuticals Corporation were 118.73 crore.
That meant four cases of privatisation got the government only 2,818.73 crore. Critics of the government’s privatisation policy have not yet latched on to this number, but when they do, reservations about the policy on strategic sale of PSUs will only get more serious.
Disinvestment receipts trail PSU dividends
In the last twelve and a half years of the Modi government, total disinvestment receipts are estimated at 4.37 trillion, of which privatisation proceeds account for a tiny proportion of just 0.64 per cent, with the remaining amount being collected through the sale of minority shares.
In the last one and a half years, asset monetisation (or the sale of land and buildings owned by government-owned PSUs) has picked up, with a total amount estimated at 34,787 crore. Even after including asset monetisation, total disinvestment proceeds in the Modi regime so far have been less than PSU dividend receipts of 5.32 trillion during this period.
This is perhaps one of the reasons for the government slowing down its disinvestment programme from 2021-22, ironically the same year when the government announced its policy on strategic sale of PSUs.
It was argued by senior finance ministry functionaries then that value maximisation was as important an objective in managing PSU assets as achieving disinvestment targets.
This reflected a shift in strategy that was no longer overly dependent on strategic disinvestment and required a broader and more holistic approach decoupled from fiscal management.
Also Read: GST’s next reform should be about making tax compliance easier for businesses
Government spending on PSUs has increased
Not surprisingly, the change in approach was visible in slowing disinvestment receipts, rising dividends from PSUs, and a sharp increase in the government’s equity contribution and loans released to PSUs in subsequent years.
Between 2021-22 and 2025-26, disinvestment receipts were estimated at just about 21 per cent of the total such proceeds during the twelve and a half years of the Modi government.
In the same period, however, PSU dividends rose to 3.35 trillion, accounting for 63 per cent of total received by the government. And the government’s equity and loans to PSUs in this period rose to 21.45 trillion, over 57 per cent of what was allocated from 2021-22 to 2026-27.
It was during the same period that the government’s Budget documents stopped referring to disinvestment in its capital receipts calculations. In what seemed to be part of its plan to de-emphasise disinvestment, all receipts from asset sales were classified as non-debt capital receipts.
Three parameters to track as policy shifts
Now that the government’s approach to disinvestment is changing, it will be important to keep track of a few parameters of the government’s receipts and expenditure allocations. One, it will be helpful if disinvestment receipts and asset monetisation receipts are clearly identified in the receipts budget, so that these numbers can be easily identified and subjected to analysis and dissemination.
Two, tracking disinvestment numbers will be important. But equally important will be the need to measure the pace at which the government is investing in PSUs through equity contribution and loans. In the early years of the Modi government, the amount allocated for equity and loans to PSUs was a little more than a third of the government’s total capital expenditure budget.
In the last few years, this share has been close to 50 per cent. This trend should be reversed without any decline in the government’s overall capex target.
Third, it will be necessary to keep a close watch on the ratio between the government’s total receipts from PSUs (through disinvestment and dividend income) and the amount it spends on them through equity and loans.
In the last five years, the amount of government receipts from PSUs as a share of total spending on PSUs has steadily fallen from around 30 per cent in 2021-22 to 15 per cent in 2024-25, before recovering a bit to about 26 per cent in 2025-26. This ratio should get better over time as the government’s disinvestment receipts increase and the need for fresh equity infusion declines.
AK Bhattacharya is the Editorial Director of Business Standard. He tweets @AshokAkaybee. Views are personal.
(Edited by Maryam Hassan)