
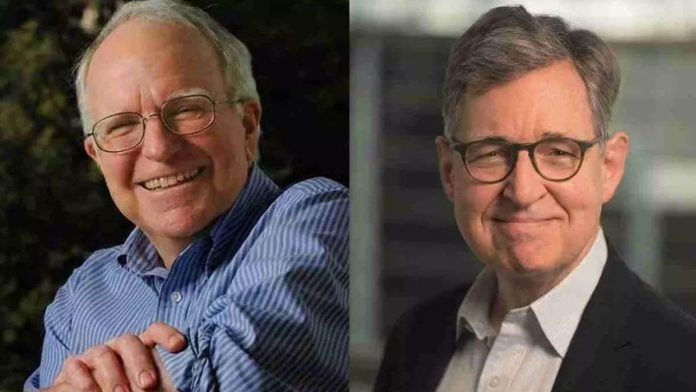
New Delhi: The Royal Swedish Academy of Sciences on Monday awarded the Nobel Prize in Economics 2026 to US economists Robert Hall and Michael Woodford for their research on ‘Microeconomic foundations of macroeconomic stabilisation.’ The two academics have contributed to the New Keynesian paradigm, which seeks to explain how governments and central banks can smooth out the economy during periods of fluctuation.
This year’s Nobel Prize, officially called the Sveriges Riksbank Prize in Economic Sciences, focuses on macroeconomics, the study of broad economic measures such as GDP, inflation, national consumption, and economic growth. The award carries a prize of 12 million Swedish kronor or about $1.2 million.
British economist John Maynard Keynes is credited with developing macroeconomics as a separate school of thought, with his work on aggregate demand (overall consumer demand) and its correlation with economic activity, and on how governments can stimulate or slow down the economy through fiscal policies.
However, Hall and Woodford, half a century after Keynes’ seminal The General Theory of Employment, Interest and Money was published, showed that aggregate demand does not always have a straightforward relationship with inflation and unemployment.
In 1978, Hall wrote a seminal article outlining how household consumption actually depended on people’s expectations of future income, rather than just on their present income. This utilised a microeconomic perspective to analyse a macroeconomic variable like household consumption.
Adding to that, in 2003 Woodford built an entirely new framework, known as the New Keynesian paradigm, which incorporated Hall’s consumption theory into a model of how government policies and fiscal decisions on taxes, interest rates and direct cash transfers can change businesses, households and economies. “The laureates’ work has provided us with a stable theoretical foundation for the models that are now used by central banks and governments around the world,” said John Hassler, Chair of the Committee for the Prize in Economic Sciences, in a press release.
Why was this new model needed?
Standard Keynesian economics, while fundamental, provides too simplistic a formula for how governments can change economic growth. According to Keynes, during recessions the government should reduce interest rates and spend more to boost the economy, and during inflation, it should do the opposite.
However, these formulations were made and were effective during the Second World War. It was in the 1970s, during the global oil crisis, that Western economies saw rising inflation even during high unemployment, and the link between income and consumption and other macroeconomic variables was not as linear as Keynesian economics had predicted.
Hall and Woodford’s work showed macroeconomic variables as being influenced by underlying microeconomic foundations.
Also Read: Canadian author Anne Carson wins Literature Nobel Prize for ‘reinventing’ classical works
Robert Hall and Michael Woodford
83-year-old Robert Hall, a professor of economics at Stanford University, is an applied economist who has worked with US government departments on national economic policy. His main work on household consumption in 1978 was important in explaining that households make rational, forward-looking decisions and prefer to plan their spending in the long term.
“Hall presented his results in an article in 1978, which was something of a eureka moment for research. His work became key to the development of modern research on consumption,” said the Nobel Committee.
Meanwhile, Woodford, a professor of economics and monetary policy at Columbia University, has worked strictly on theoretical foundations of macroeconomics and fiscal policies of governments, with his most famous work titled ‘Interest and Prices: Foundations of a Theory of Monetary Policy.’
His work was seminal in expanding the Keynesian model to incorporate real-world factors such as forward-thinking household consumption and the fact that prices and wages do not immediately change given an economic disruption.
Woodford termed these ‘sticky prices’, which indicate that when demand falls, businesses will first reduce output and cut costs before increasing their prices.
Moreover, Woodford also made a case for how governments can influence inflation or recession by changing interest rates, something that is still used widely in mainstream monetary policy.
These real-world indicators made the New Keynesian model more palatable, and thus helped a generation of governments and central banks work through macroeconomic crises, explained the Nobel Committee’s press release.
(Edited by Maryam Hassan)