
Victims of financial fraud lost almost $500 billion last year, based on surveys in 42 countries. Yet the staggering sums aren’t the most alarming part. Fraud is becoming more sophisticated and global, turning what was once a collection of isolated scams into a sprawling cross-border business.
In Southeast Asia, criminal activities are highly centralized: A scam compound in the Mekong region — in Myanmar, or on the Thai-Cambodia border — can hunt for marks in more than 100 countries.
Recruitment itself is a form of cross-border trafficking. Poor, unemployed people are lured overseas with promises of legitimate work, only to be trapped in compounds and forced to defraud strangers online. According to the UN Human Rights Office, at least 120,000 people in Myanmar — and roughly 100,000 in Cambodia — have been held for that purpose. Families have to pay ransoms for their release; often employees must recruit their own replacements.
To evade detection, however, syndicates are increasingly splintering into smaller units, dispersing across hotel rooms, offices, and even coffee shops. In Europe, that networked model was deployed by a fake-investment racket operating 20 call centers across multiple countries. More than 700 people worked under central coordination, generating roughly $113 million a month before Dutch police busted the operation in July.
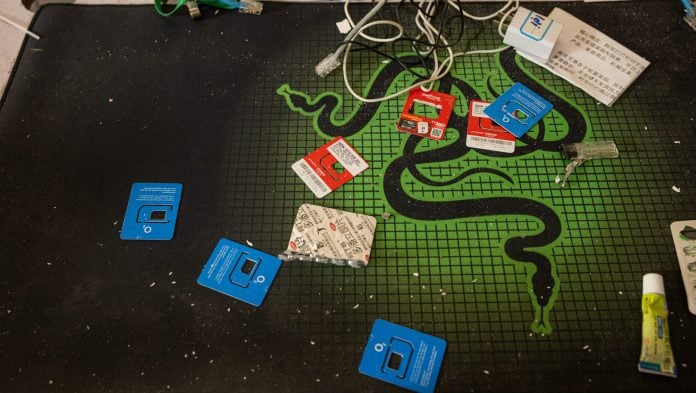
Centralized or fragmented, crime-as-a-service is a complex supply chain, where different fraud networks share a common set of vendors providing everything from SIM cards and servers to bank accounts and crypto conversion. Romance scams, Ponzi schemes, and “digital arrests” — a terrifying psychological hoax targeting Indian middle-class savers — all exploit some combination of fear, greed, and loneliness. Doing that convincingly requires more than a plausible story. Scripts must be tailored to specific demographics and continually updated; callers need the right language, accent, and cultural cues to win a victim’s trust.
Compelling narratives and credible actors are only the start. Infrastructure must be assembled, too: virtual private networks and malicious domains to be procured, workers housed and fed, and mule accounts cultivated inside the banking system to move the proceeds. Then there’s artificial intelligence. Deepfakes, voice cloning, chatbots, automated scripts, and multilingual content “can further increase the scale and sophistication of victim targeting and engagement,” according to a new Financial Action Task Force report.
The FATF study, Combating End-to-End Illicit Financial Flows Linked to Scam Compounds, should be a wake-up call for governments. Unless authorities disrupt the entire criminal supply chain, they will always be playing whack-a-mole. Raid one compound or arrest a few operators and the business merely scatters — the Middle East and Africa are emerging as new frontiers for scamming.
Criminal startups are finding it easier to expand, thanks to digital tools such as Xinbi Guarantee, a Chinese-language illicit online marketplace where merchants offered money-laundering and technology services to Southeast Asian scam compounds. In September, US authorities sanctioned Xinbi, seizing its digital wallets. Since 2022, the marketplace and its platforms have processed over $24 billion in crypto and fiat currencies, with merchants encouraged to use SafeW, an encrypted messaging application developed by a Singapore-based firm, the Treasury said. To wash the proceeds, the scamsters used XinbiPay, a payment application built in Cambodia.
Traditional policing and legacy anti-money-laundering systems are losing a race against the clock. According to the Bank of Thailand, a victim typically takes about 20 hours to realize they’ve been fleeced. Their savings can be gone in three to five minutes — shuttled through mule accounts, converted into stablecoins, and spirited beyond the regulated financial system. For a bank to file a suspicious transaction report on a mule account weeks later is merely writing an autopsy on dead money.
That time lag is what the FATF wants to eliminate. The Paris-based watchdog made its name pursuing terror financiers, drug cartels, and rogue states. It has tracked cyber fraud for years, but with scam compounds corroding trust in the global banking system, the task force is asking countries to trace their financial flows. Finance ministers ought to listen, if only to avoid the reputational scar of being placed on its “gray list.”
Action must start with payment and telecom networks. Telcos, which see the first warning signs — bursts of spoofed calls or automated text messages — should feed real-time alerts to retail banks. Payment providers, meanwhile, need to build more friction into transactions: mandatory payee-name matching, cooling-off periods for sudden large transfers, and immediate account holds when fraud is suspected. The aim is simple: intervene before a manipulated victim can click away a lifetime of savings.
Investigators must also adapt. Physical “tells” — like a sudden spike in food orders from a small office — may soon vanish. Like their counterparts in legitimate business software, crime-as-a-service operators may also embrace less labor-intensive technology. “Through the adoption of AI agents, some models may become less dependent on large trafficked workforces and the corruption associated with maintaining large physical sites, while becoming more dependent on reliable electricity, connectivity and digital infrastructure,” the FATF report notes.
The goal of law enforcement must be to choke syndicates’ ability to extract, launder, and enjoy their loot. But AI is steadily improving their margins, lowering costs, and boosting productivity across the criminal supply chain. Regulators need to act before crime-as-a-service becomes leaner — and even harder to disrupt.
Disclaimer: This report is auto generated from the Bloomberg news service. ThePrint holds no responsibility for its content.